Fifty Thirty Twenty Budget Rule
In this post
- What the fifty thirty twenty rule means
- The 50 percent needs share explained
- The 30 percent wants share explained
- The 20 percent savings share explained
- How to set up the rule step by step
- When rent eats more than half
- A worked example with simple numbers
- Common mistakes that break the rule
- Why this rule lasts when diets fail
Payday used to feel like a small festival in my house. The money arrived, the mood lifted, and for a few days everything felt possible. Then, somewhere around the third week, the festival ended. The money was gone, the month was not, and nobody could quite say where it had all gone. There was no big disaster. No single purchase ruined the month. The money simply leaked away, a little at a time, through a hundred small decisions that nobody was watching.
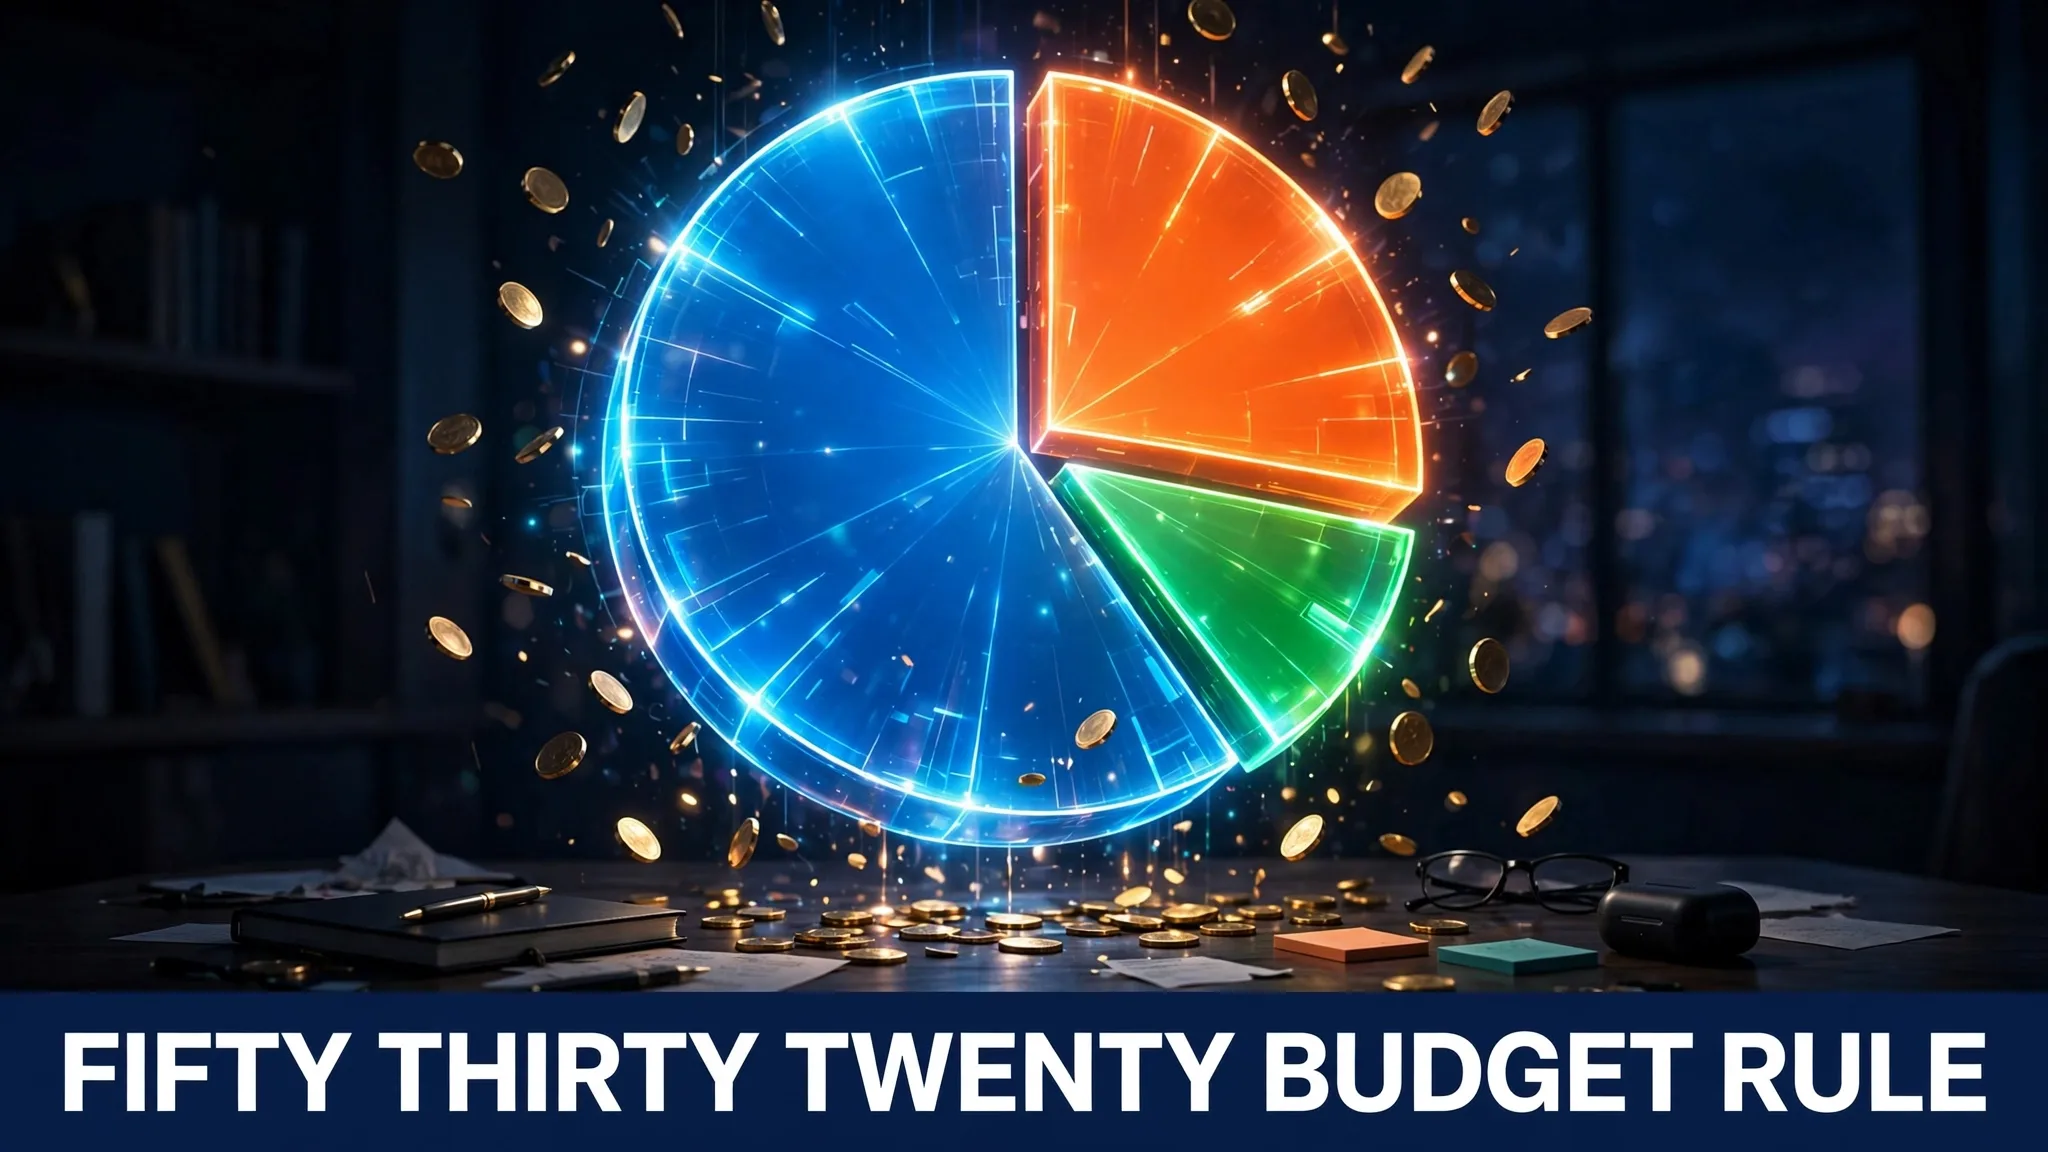
That is the exact problem the 50/30/20 budget rule was built to solve. It is not a complicated spreadsheet. It is one simple split for the money that lands in your account after tax: 50 percent for needs, 30 percent for wants, and 20 percent for savings and paying off debt. Three buckets, three numbers, and a clear answer every time you wonder whether you can afford something. The rule became widely known through a 2005 book, All Your Worth, by Elizabeth Warren and her daughter Amelia Warren Tyagi, and it has stayed popular because it is easy to remember and easy to start.
The beauty of the rule is that it does not ask you to track every coin. It asks you to sort your spending into three honest piles, and then check whether the piles are roughly the right size. If they are not, you know exactly which pile to shrink. This guide walks through each share, with real examples, so you can try the rule on your own pay.
What the fifty thirty twenty rule means
The rule starts with your after-tax income, which is the money that actually reaches your bank account after tax has been taken out. If your pay varies from month to month, use an average of recent months, or base the split on the lowest month you can count on, so the plan survives a slow month.
Then divide that money into three shares. Fifty percent goes to needs, the things you must pay to live and work. Thirty percent goes to wants, the things that make life pleasant but are not required. Twenty percent goes to savings and extra debt repayment, the money that builds your future. The three shares add up to all of your after-tax pay, so every unit of money has a job before the month begins.
The percentages are targets, not laws. Prudential, the financial services company, describes the rule as a guideline that helps people think about the balance between spending now and saving for later. If your rent is very high, your needs share may run above 50 percent, and that does not mean you have failed. It means you adjust the other two shares for now and work on the biggest cost when you can.
The 50 percent needs share explained
Needs are the bills you cannot skip without real harm. Housing comes first: rent or a mortgage payment. Then groceries, the food you cook and eat at home. Then transport to work, whether that is fuel, bus fare, or a car payment you need to keep your job. Utilities follow: electricity, water, gas, and the phone and internet connection you need for daily life.
Insurance belongs in needs too, because one uninsured accident can cost far more than a year of premiums. Clothing you genuinely need, minimum payments on debts, and childcare costs while you work also count as needs. Prudential lists all of these — housing, groceries, transport, utilities, insurance, clothing, minimum debt payments, and childcare — as the core of the needs share.
The test for a need is simple and a little uncomfortable: if you stopped paying for it, would your health, your home, or your job suffer soon? If the answer is yes, it is probably a need. If the answer is no, it probably belongs in the next bucket, however much you enjoy it.
The 30 percent wants share explained
Wants are the extras that make life enjoyable. Eating at restaurants, takeaway coffee, streaming subscriptions, holidays, hobbies, concerts, new gadgets, and gifts all live here. None of them are shameful. A budget with no room for pleasure is a budget nobody keeps, and the 30 percent share exists precisely so that fun has a place and a limit.
The trouble starts when wants quietly dress up as needs. A basic phone plan is a need; the newest phone every year is a want. Groceries are a need; a fancy dinner out is a want. A haircut is a need for most people; a luxury salon treatment every week is a want. Sorting honestly is the whole skill, and it is worth doing slowly the first time, because the first sort is the one that teaches you where your money really goes.
Wants are also the easiest share to adjust. When money is tight, the wants bucket shrinks first, without touching rent or food. When money is comfortable, the wants bucket can grow a little, as long as the savings share is already funded. That flexibility is why the rule survives real life better than a rigid plan.
The 20 percent savings share explained
The last share is the one that changes your future. Twenty percent of after-tax pay goes to savings and to paying down debt beyond the minimum payments. Prudential describes this share as covering an emergency fund, debt repayment, and retirement savings, and suggests building an emergency fund that can cover six to twelve months of expenses over time.
If 20 percent sounds impossible, start smaller. Even a small automatic transfer on payday, made before you can spend the money, builds the habit. The habit matters more than the first amount, because a habit can grow when pay rises, while a plan that demands too much on day one usually collapses by week three. Many people find that paying themselves first — moving the savings out on payday — works better than saving whatever is left at month end, because at month end there is rarely anything left.
Debt repayment in this share means extra payments above the minimum. Minimum payments are needs, already counted in the 50 percent. Anything extra you pay to clear a card or a loan faster comes from the 20 percent, and it earns you a guaranteed return, because every unit of debt cleared is interest you will never pay.
How to set up the rule step by step
Start by writing down your after-tax pay for one month. Then list every regular expense and sort each one into needs, wants, or savings. Do not guess from memory alone. Prudential suggests tracking your spending for two to three months before finalising the split, because memory flatters us and receipts do not.
Next, add up each pile and compare it with the 50/30/20 targets. Most people discover one surprise: a subscription they forgot, a food delivery habit that costs more than the groceries, or a transport cost that quietly eats a quarter of the month. The surprise is the point. Once you see it, you can decide what to do about it, and the decision is yours, not the budget’s.
Then set the transfers. Move the savings share out of your spending account on payday, into a separate account you do not dip into casually. Pay the fixed needs first. Give the wants share a clear limit, in cash or in a separate account, so you can see it shrinking through the month. A limit you can see is a limit you can respect.
When rent eats more than half
In expensive cities, housing alone can take 50 percent or more of after-tax pay, and the neat split breaks before it starts. This is common, and it is not a personal failure. The rule is flexible, and Prudential notes that people in high-cost areas may need to adjust the shares, spending more on needs and less on wants and savings for a time.
When needs run high, protect the savings habit even if the amount is small. A tiny automatic transfer kept every month matters more than a perfect 20 percent that never happens. Then look at the biggest cost with fresh eyes: a cheaper area, a shared home, a shorter commute, or a renegotiated rent at renewal time. Small trims to ten small expenses rarely fix a housing problem, but one change to the biggest bill can restore the whole balance.
The same honesty applies in reverse. If your needs share is well below 50 percent, do not let the whole difference slide into wants. Push the extra toward savings and debt first, and let the wants share grow only after the future is funded. The rule rewards the person who treats a low rent as an opportunity, not as permission to spend.
A worked example with simple numbers
Imagine a monthly after-tax pay of 100,000 in any currency. The rule gives 50,000 for needs, 30,000 for wants, and 20,000 for savings and extra debt payments. Rent takes 25,000, groceries 12,000, transport 6,000, utilities 4,000, and insurance and minimum debt payments take the remaining 3,000. The needs pile is full and honest.
The wants pile of 30,000 then covers eating out, streaming, a hobby, and a small gift budget, and nothing more. When a friend suggests a weekend trip that would cost 15,000, the answer is visible at once: half the month’s wants money in one trip, leaving little for everything else. That visibility is the rule doing its job, not ruining the fun.
The savings pile of 20,000 splits in two while an emergency fund is still growing: perhaps 12,000 into the emergency fund and 8,000 as an extra payment on the most expensive debt. Once the emergency fund is full, the whole 20,000 can turn toward debt, then toward long-term saving. The numbers are simple, the order is clear, and the month has a shape before it begins.
Common mistakes that break the rule
The first mistake is sorting with soft eyes, calling wants by the name of needs until the needs pile holds everything and the savings pile holds nothing. Be strict in the first sort. A second mistake is setting the plan once and never looking at it again. Prices rise, pay changes, and a plan from January may not fit October. Check the split every few months, and adjust without guilt.
A third mistake is forgetting irregular costs. A yearly insurance bill, a festival season, school fees, or a car repair are not surprises if they happen every year. Divide their yearly cost by twelve and keep that amount inside the monthly plan, so the big month does not wreck the budget. A fourth mistake is aiming for perfection in week one. A rough 50/30/20 split followed for three months beats a perfect spreadsheet abandoned in ten days.
Why this rule lasts when diets fail
Most budgets fail because they demand too much attention forever. The 50/30/20 rule asks for attention once, at the sorting stage, and then runs on three numbers. You do not need to record every snack. You need to know which pile the snack comes from, and whether that pile still has room.
It also lasts because it is kind. A budget that bans all pleasure teaches people to hide spending, and hidden spending grows. A budget that gives pleasure a fair share — 30 percent is generous — removes the shame and keeps the spending visible. Visible spending can be managed. Hidden spending cannot.
The rule will not make anyone rich in a month. What it does, month after month, is stop the quiet leak, build a cushion, and turn payday from a festival that ends in worry into a routine that ends in calm. That calm is the real product, and it is worth more than any single purchase the wants pile ever buys.
Frequently Asked Questions
How does the 50/30/20 budget rule work for a low salary?
The rule works the same way at any pay level, because it is a proportion, not a fixed amount. You take your after-tax pay and aim for 50 percent on needs, 30 percent on wants, and 20 percent on savings and extra debt payments. If rent is high and needs run above 50 percent, adjust the other shares for now and protect even a small savings habit, because the habit matters more than hitting 20 percent in the first month.
What counts as a need in the 50/30/20 budget rule?
Needs are the costs you must pay to live and work: housing, groceries, transport, utilities, insurance, clothing you genuinely need, minimum debt payments, and childcare while you work. The test is whether skipping the payment would soon harm your health, your home, or your job. A basic phone plan is a need, while the newest phone every year is a want, and sorting honestly between the two is the key skill in the whole rule.
What counts as a want in the 50/30/20 budget rule?
Wants are the extras that make life pleasant but are not required: restaurants, takeaway coffee, streaming subscriptions, holidays, hobbies, concerts, new gadgets, and gifts. The 30 percent share gives fun a place and a limit, so pleasure is planned instead of hidden. Wants are also the easiest share to shrink when money is tight, because cutting them does not touch rent, food, or other essentials.
How much emergency fund should the 20 percent share build?
The 20 percent share covers savings, extra debt repayment, and retirement saving, and Prudential suggests building an emergency fund that can cover six to twelve months of expenses over time. That is a long-term target, not a first-month demand. Start with a small automatic transfer on payday and grow it when pay rises, and split the share between the emergency fund and extra debt payments until the fund is strong.
Who invented the 50/30/20 budget rule?
The rule became widely known through the 2005 book All Your Worth by Elizabeth Warren and her daughter Amelia Warren Tyagi. It has stayed popular because it is easy to remember: three shares for after-tax pay, checked against real spending tracked over two or three months, and flexible enough to adjust when housing costs or other needs run high.
Sources
- Prudential — Budgeting: The 50/30/20 Rule (fetched 2026-10-28)